Trump’s One Big Beautiful Bill is Now Law: How it Impacts Solar
2026 update: The homeowner credit is gone. Under the One Big Beautiful Bill, homeowners who buy solar or a battery with cash or a loan get no federal tax credit in 2026. The credit's value still reaches homeowners through a Prepaid TPO, a prepaid lease: a partner holds the system for its first five years, claims the business credit and takes that amount off your price at the start. After year five, ownership passes to you.
On July 4, 2025, Donald Trump signed his megabill, called the “One Big Beautiful Bill” or OBBB for short, into law. The OBBB solar provisions and implications are vast. With the preface that solar.com is not providing legal or tax advice, here’s what you need to know about this Megabill’s direct and indirect impacts on residential solar.
Solar.com’s One Big Beautiful Bill Resource Center:
- FAQs about the OBBB
- Homeowner guide to going solar in the OBBB rush
- Archive: tracking the OB3 through the House and Senate
See it for your home
Get your real solar price in 90 seconds
Enter your address — we’ll show the system, savings, and price for your exact roof. No sales calls.
Big Beautiful Bill Summary: What Does it Mean for Solar?
The headline change to solar from the OBBB is that the 30% solar tax credits are ending. The credit for homeowners who buy their system already ended at the end of 2025. However, there are important distinctions between the different types of tax credits and their phase-out schedules.
The 30% Consumer Solar Tax Credit (25D)
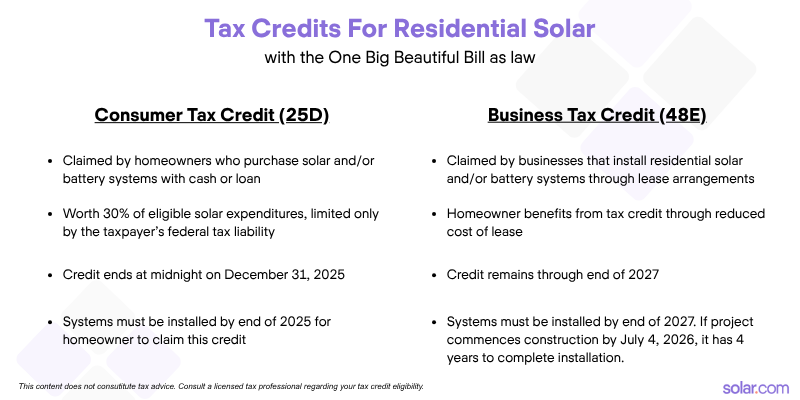
The consumer claimed tax credit under Section 25D ended at the end of 2025. These credits were claimed by consumers who own their own solar array (and/or battery storage system), either by paying cash or financing it through a loan. The language in the bill specifically states that “expenditures made” after December 31, 2025 are not eligible to be claimed by individuals on their federal tax returns.
The IRS confirmed on August 21, 2025 that the system had to be fully installed by the end of 2025 to qualify. Signing a contract or placing a deposit was not enough to meet the “expenditures made” threshold.
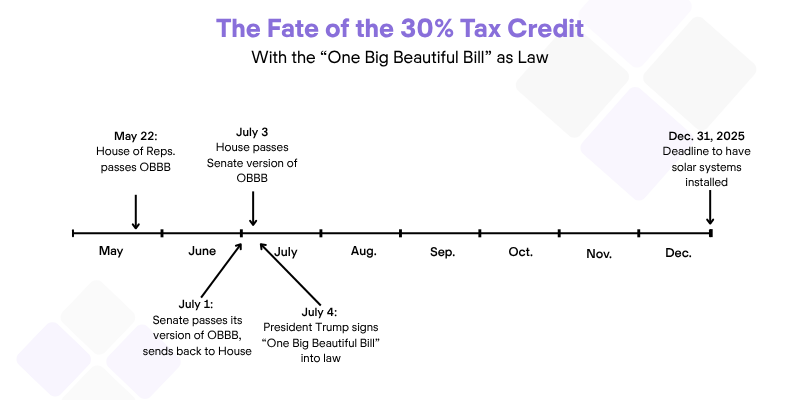
Many sales originators and installation companies reported record homeowner demand for solar as the OBBB worked its way through the House and Senate.
See it for your home
Get your real solar price in 90 seconds
Enter your address — we’ll show the system, savings, and price for your exact roof. No sales calls.
Solar Tax Credits for Leases, PPAs, and Businesses (48E)
The business tax credit for solar, claimed under Section 48E, ends at the end of 2027, but with an important distinction. Homeowners who go solar after 2025 can still benefit from the tax credit through a Third-Party Ownership (TPO) arrangement. TPO solar is typically in a lease or Power Purchase Agreement structure where a business owns the solar array and sells the power back to the homeowner, either at a fixed rate (lease) or on a per kWh basis (PPA).
Since the solar array is owned by a third party, they claim the tax credits under section 48E, which stays open until the end of 2027. The value of the tax credit (and depreciation), which is claimed by the TPO, reduces the cost of the lease or PPA. So while the 25D tax credit can’t be claimed by homeowners directly after 2025, entering into a TPO structure still allows homeowners to benefit from the 48E tax credit.
Review solar.com’s consumer guide to leases with the One Big Beautiful Bill as law.
The 48E “loophole” for residential solar
Since tax credits for Third-Party Owned residential solar are claimed under the same section of the tax code as very large solar projects, they benefit from the same tax treatment. The OBBB contemplates that the “mega” projects take years to develop and construct, so ending the tax credits clean at the end of 2027 would likely strand billions of dollars of investment and would have serious negative impacts on the electric grid. Interconnection queues in the US are filled with far more solar than any other type of generation technology, and society needs that power.
The loophole gives projects that Commenced Construction by July 4, 2026, one year after the bill was signed, up to four years to be placed in service and claim the tax credit. This is known as a safe harbor rule, and largely applies to utility and commercial-scale projects that can take years to complete.
There are a few ways for companies to demonstrate they Commenced Construction by July 4, 2026, and residential solar companies will likely utilize these strategies to continue to offer tax credit advantaged leases and PPAs post 2027. Why does this matter? Investing in solar is a significant commitment, and having confidence the manufacturers and installers involved in your project are around to support the installation is important. This extra runway will help create a glide path for parts of the industry to evolve into a post-tax credit economic model.
On July 7, 2025, President Trump issued an Executive Order directing agencies to deliver a report regarding safe harboring rules within 45 days, specifically relating to how the Treasury defines “commence construction.” The Treasury answered with IRS Notice 2025-42, which sets out what counts as commencing construction for wind and solar projects. Given the faster construction cycle for residential leases, this Executive Order likely won’t have much effect on homeowners.
Energy Storage Tax Credit Retention
Energy Storage Systems (ESS) or batteries retained their tax credits under 48E (third-party owned) through 2033 before a phase-out occurs. This is the same tax credit phase-out schedule for nuclear, geothermal, and hydro. However, these projects must comply with FEOC rules (see below).
The preservation of ESS tax credits under 48E helps protect homeowners who invest in solar today but may face utility rate changes in the future that devalue solar exported back to the grid. Having the option to install a battery through a lease arrangement at a later time will help preserve the value of solar. (Note – it’s always better, and more cost-efficient, to install both solar and ESS at the same time, when possible).
Manufacturing Tax Credits (45X)
The US has seen a renaissance in US manufacturing since the IRA was passed, with factories capable of producing over 50 GW of annual solar panel production either brought online or under construction. These factories created billions of dollars in economic investment and created, collectively, tens of thousands of jobs. The OBBB acknowledged these facts and preserved the 45X solar tax credits through 2032.
However, a lot of factories were placed in the US by Chinese-owned or controlled companies, and those factories will likely lose access to the 45X credits under FEOC restrictions.
While this has lower relevance to homeowners than the consumer-facing tax credits, it’s important to consider whether the company and factory supplying the technology to an individual’s project will be able to support warranty claims for the life of the system.
Restriction of Tax Credits that Benefit Foreign Entities of Concern (FEOC)
One of the major changes to energy tax credits under the OBBB compared to the IRA is the restrictions on Foreign Entities of Concern from benefiting directly or indirectly from US taxpayer support. The FEOC rules are complex and voluminous, impacting both the supply and demand parts of the value chain. Simply put, an FEOC country is a “Foreign Entity of Concern” and, for practical application in the solar industry, effectively references Chinese companies.
FEOC rules had no direct implication for homeowners who finished a project in 2025 to claim the consumer tax credit under 25D. However, homeowners should be considerate of whether factories and companies will stay in the US market after the restrictions take effect. Simply having a US entity operating a US factory is insufficient in the long-term, as it also considers whether the company has FEOC debt or equity above certain ratios, FEOC nationals as Executive members, rely on intellectual property from FEOC companies, whether its principle place of business is in a FEOC country, or other metrics defined by the law.
Even non-FEOC companies face FEOC restrictions under “material assistance” rules, which phase in starting in 2026 and examine the percentage of FEOC subcomponents in a project relative to non-FEOC components.
The good news is that businesses monetizing the tax credits under Section 48E will run the audits and take the risks on claiming tax credits under the complex FEOC restrictions.
Solar Thermal Tax Credits
Tax credits to support solar thermal applications (hot water) have ended for both consumer (25D) and business (48E) claims.
Energy Efficiency Tax Credits
The consumer tax credit for home energy efficiency upgrades, Section 25C, ended at the end of 2025 under the OBBB.
EV Tax Credits Ending
New and used tax credits for purchasing an electric vehicle ended on September 30, 2025, in an accelerated phase-out of the tax credits to encourage consumers and businesses to adopt electric vehicles.
A Final Note
Our editorial team works hard to keep this guide accurate and easy to follow. If you spot something we missed or got wrong, email us at newsroom@solar.com. And if this article helped with your own OBBB research, a link back to it helps other homeowners find it.
Homeowners who understand the rules make better solar decisions. If this guide helped, the best thanks is to get no-obligation prices online for your own home solar project. We never sell or remarket your information, and our design and support teams will guide you through each step with the same care we put into articles like this one.
Your next step
See exactly what solar costs on your roof
We use satellite data and your utility rates to show your price and payback in about 90 seconds, with no sales calls.